

FE610—The Quantity Theory of Money
Foundation of Monetary Integrity
Summary:
The Quantity Theory of Money (QTM) is one of the oldest and most resilient ideas in monetary economics. From Copernicus through Hume and Friedman, economists have recognized that the supply of money cannot become disconnected from economic production without consequences. Although QTM is often presented primarily as an explanation of inflation, FE610 argues that its deeper significance lies in a more fundamental principle: money must maintain a meaningful relationship with the creation of real value. This principle is described here as Monetary Integrity—the degree to which a monetary system faithfully represents the creation of real value within society. FE610 traces the historical development of QTM, examines the promise and limitations of Monetarism, and identifies an unresolved question: Can Monetary Integrity be maintained within large, dynamic economies operating through highly centralized monetary systems?
1.0 Why the Quantity Theory of Money Matters
Money is one of humanity’s most remarkable inventions. It enables strangers to cooperate, allows knowledge to be transmitted through prices, and permits economic activity to span both time and distance. Every modern economy depends upon money, yet surprisingly few people ever stop to ask why money has value or why society should trust it.
Throughout history, civilizations have struggled with the same fundamental challenge: how can a society ensure that its money continues to represent genuine economic value?
One of the oldest and most influential attempts to answer that question is the Quantity Theory of Money (QTM). Although today it is often introduced as a theory explaining inflation, its historical significance extends much deeper. At its heart, the Quantity Theory of Money expresses a simple but profound principle: The supply of money should bear a meaningful relationship to the production of real value within society.
When that relationship is preserved, money serves as a trustworthy medium for exchange, pricing, saving, and investment. When the relationship breaks down, money gradually loses its ability to communicate economic reality.
Inflation is one consequence of that failure, but it is not the underlying problem. The deeper issue is one of monetary integrity. A monetary system cannot remain trustworthy if the symbols used to represent value become detached from the value they are intended to represent.
For more than five centuries, economists have explored this relationship. Their conclusions have differed in important ways, yet many shared a common intuition: money cannot be treated as an independent source of wealth. It must remain connected, in some meaningful way, to the productive activity of the society that issues it.
Understanding that principle is the purpose of this essay.
2.0 The Historical Development of the Quantity Theory of Money
Although QTM is commonly associated with modern economics, its origins reach much further into history. One of the earliest systematic discussions appeared in 1517 when Nicolaus Copernicus observed that excessive debasement and expansion of the money supply diminished the purchasing power of currency. Writing in an era when coins derived much of their value from precious metals, Copernicus recognized that the integrity of money depended upon preserving a consistent relationship between the money in circulation and the value it represented.
Copernicus: Economist as Well as Astronomer
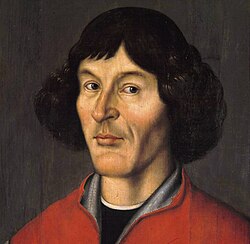 Nicolaus Copernicus
An Early Foundation for the Quantity Theory of Money
Nicolaus Copernicus is best remembered for proposing that the Earth revolves around the Sun, but his interests extended well beyond astronomy. He also studied the monetary problems of his time, particularly the repeated debasement of coinage.
Beginning in the early sixteenth century, Copernicus developed arguments connecting the quantity and quality of money in circulation with its purchasing power. He recognized that increasing the supply of money without a corresponding increase in underlying economic value could diminish what each monetary unit could buy. He also described how debased money could drive better money from circulation—an observation later associated with Gresham’s Law.
Copernicus’s monetary writings preceded modern economics by centuries, yet they anticipated a principle that would become central to the Quantity Theory of Money: money cannot be manipulated independently of the economic value it represents without consequences.
Learn more about Copernicus and the Quantity Theory of Money here.
Several decades later, Jean Bodin examined the dramatic rise in European prices following the influx of precious metals from the Americas. Rather than attributing higher prices solely to greed or market failures, Bodin argued that expanding quantities of money played a significant role. His work helped shift economic thought toward understanding inflation as a monetary phenomenon rather than merely a commercial one.
John Locke further developed these ideas by emphasizing the importance of a stable currency. He argued that governments should resist the temptation to manipulate the value of money through debasement or arbitrary alteration of coinage. Stable money, in his view, encouraged trust, investment, and long-term prosperity.
David Hume refined the theory by observing that increases in the money supply do not immediately raise all prices simultaneously. Instead, new money enters the economy through particular individuals and industries before gradually spreading throughout society. His observations anticipated many later discussions concerning the uneven effects of monetary expansion.
The nineteenth and twentieth centuries brought increasingly mathematical treatments of the theory. Irving Fisher expressed the relationship through his famous equation:
MV = PQ
Where money multiplied by its velocity equals the price level multiplied by the quantity of transactions or output. The equation did not create the Quantity Theory of Money. Rather, it provided a concise mathematical expression of ideas that had been developing for centuries.
In the twentieth century, Milton Friedman revitalized the theory through Monetarism. His often-quoted observation that “inflation is always and everywhere a monetary phenomenon” emphasized the importance of controlling the growth of the money supply. Although debates continue regarding the details of monetary policy, Friedman’s work restored the Quantity Theory of Money to the center of economic discussion. At least temporarily.
Across five centuries, these thinkers differed in methodology and emphasis, yet they shared a common concern: preserving confidence in money by maintaining a meaningful relationship between the money circulating within an economy and the productive capacity of the society using it.
3.0 What the Quantity Theory of Money Really Says
Most students first encounter the Quantity Theory of Money through the equation MV = PQ. Unfortunately, many stop there. The equation is useful because it illustrates an important relationship among money, spending, prices, and production. Yet the equation itself is not the theory.
The theory is the principle that the equation attempts to express. The Quantity Theory of Money recognizes that money does not create wealth simply by existing. Printing or minting additional currency cannot by itself increase society’s productive capacity, invent new technologies, educate workers, or build factories. Wealth arises from people creating goods, services, knowledge, institutions, and other forms of value. Money serves as a representation of those achievements rather than their source.
When the quantity of money expands much faster than the value being created, purchasing power tends to decline. When money becomes unnecessarily scarce relative to economic activity, productive exchange may also suffer. In either case, the relationship between money and underlying value becomes distorted. Seen from this perspective, the Quantity Theory of Money is fundamentally concerned with correspondence. It seeks to preserve a meaningful relationship between monetary representation and economic reality.
That principle remains relevant even when economists disagree about the precise measurements involved. Velocity changes. Productivity changes. Financial institutions evolve. Global trade introduces additional complexity. Nevertheless, the underlying concern remains remarkably consistent: money functions best when it faithfully reflects the productive life of society.
4.0 Monetary Integrity: The Principle Behind the Quantity Theory of Money
Throughout its long history, the Quantity Theory of Money has often been presented as a theory of inflation. While inflation is undoubtedly one of its most important applications, viewing the theory solely through that lens risks overlooking its deeper contribution. At its core, the Quantity Theory of Money is concerned with preserving the trustworthiness of money itself.
Money performs many functions. It serves as a medium of exchange, a unit of account, and a store of value. Yet none of these functions can endure unless people have confidence that money continues to represent the economic reality of the society using it. A monetary system loses credibility when the symbols used to measure value become increasingly detached from the value they are intended to represent. This underlying principle deserves a name.
Monetary Integrity is the degree to which a monetary system faithfully represents the creation of real value within society. That definition does not prescribe a particular monetary system. It does not require gold, fiat currency, cryptocurrency, or any specific institutional arrangement. Rather, it describes the standard by which any monetary system should ultimately be judged.
A system possessing high monetary integrity maintains a meaningful relationship between the money it issues and the productive achievements of the society it serves. A system with declining monetary integrity gradually weakens that relationship. Money may continue to circulate, prices may still be quoted, and transactions may still occur, yet the currency becomes a progressively less reliable representation of underlying economic reality.
Seen from this perspective, inflation is not the principle that the Quantity Theory of Money seeks to explain. Inflation is one visible symptom that monetary integrity has been compromised. Likewise, persistent deflation, severe monetary instability, or repeated financial distortions may also reflect failures to preserve that same underlying relationship. The precise symptoms may differ, but the principle remains the same.
This distinction is important because it shifts attention from the symptoms to the condition that produces them. Just as a physician seeks to understand the health of the patient rather than merely suppress individual symptoms, sound monetary policy should seek to preserve the integrity of the monetary system itself rather than simply reacting to changing prices.
Of course, no monetary system can perfectly measure every form of value created within a modern economy. Human knowledge is incomplete. Innovation continually creates new forms of wealth that are difficult to quantify. Institutions evolve. Preferences change. Economic conditions never remain static.
Yet these realities do not diminish the importance of monetary integrity. On the contrary, they explain why preserving it has proven to be such a persistent challenge throughout history.
Viewed in this light, the enduring significance of the Quantity Theory of Money extends well beyond its mathematical expressions or policy debates. For more than five centuries, some economists have sought to preserve a meaningful relationship between money and the productive life of society. Although they often approached the problem from different directions, they shared a common concern: That money cannot remain trustworthy indefinitely if it becomes disconnected from the creation of real value.
That concern—the preservation of monetary integrity—may ultimately be understood as the Quantity Theory of Money’s most enduring contribution.
5.0 The Promise and Limits of Monetarism
The revival of QTM during the twentieth century demonstrated the continuing importance of monetary discipline. Monetarism reminded governments that creating additional money cannot substitute for genuine economic productivity. Money cannot indefinitely become disconnected from the economic value it represents. Yet translating that principle into monetary policy proved considerably more difficult.
Modern economies are extraordinarily complex. Production includes not only physical goods but also software, intellectual property, education, scientific research, digital services, and countless forms of intangible value. Even determining which monetary aggregates are most relevant can be problematic. Rather than attempting to measure value creation directly, Monetarism generally sought discipline through rules limiting the growth of the money supply. Such rules could constrain excessive monetary expansion, but they could not establish a precise correspondence between new money and new value creation.
Monetarism also faced substantial intellectual, institutional, and political resistance. Monetary discipline, by definition, constrains monetary discretion. Competing economic theories favored greater flexibility for policymakers, while the practical difficulties of monetary targeting provided additional reasons for reducing Monetarism’s influence and questioning the importance of the Quantity Theory.
These difficulties did not invalidate QTM. Instead, they exposed an important distinction: Recognizing the need for Monetary Integrity and reliably maintaining it are two different problems. The first is a principle. The second is an implementation challenge.
6.0 The Unresolved Question
Even if one adopts a central insight of the Quantity Theory of Money—the importance of maintaining a meaningful correspondence between money and economic production—it does not, by itself, explain how that relationship can be reliably maintained.
As we have seen, value is continually created throughout a complex economy through production, innovation, discovery, improved efficiency, knowledge, services, and other forms of human achievement. Identifying and measuring that value becomes increasingly difficult as an economy grows ever larger and more complex. Consequently, no monetary system has yet demonstrated a reliable means of identifying and acting upon this dispersed information while consistently preserving Monetary Integrity.
This leaves an unresolved question: Can Monetary Integrity be maintained within large, dynamic economies operating through highly centralized monetary systems? Is that even possible?
7.0 Conclusion
For more than five centuries, the Quantity Theory of Money has expressed a fundamental principle: Money cannot remain trustworthy when its supply becomes disconnected from the creation of real economic value.
This principle can be understood as Monetary Integrity—the degree to which a monetary system faithfully represents the creation of real value within society. Inflation is one possible consequence when that integrity deteriorates, but the deeper concern is the relationship between monetary representation and economic reality.
This essay is the first of four works comprising U2D2’s 1517 Series, named for the year Nicolaus Copernicus first explored what would later become known as the Quantity Theory of Money. (See sidebar above.) The remaining papers in this series address the unresolved question identified in Section 6.0 above.
WP610—What Is Money? Reframing Currency as Liquid Human Achievement—examines what money represents.
FE907—Quantity Theory of Money—Decentralized—examines the implications of centralized monetary issuance.
WP907—Value-Linked Currencies (VLCs): A Decentralized Architecture for Monetary Issuance—explores how monetary issuance might instead be connected to validated value creation.